Scott Bessent’s wobbly house
Unlock the White House Watch newsletter for free
Your guide to what Trump’s second term means for Washington, business and the world
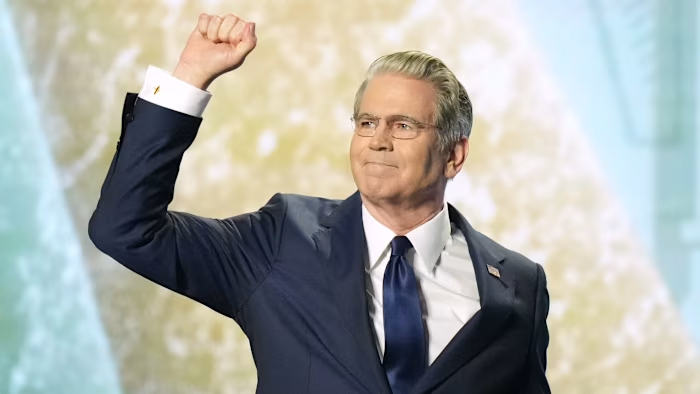
“Credibility” is a Washington measure devalued by overuse. The credibility of what the US Treasury secretary says, however, can be gauged minute by minute. For reasons even his defenders find hard to explain, Scott Bessent has been on a credibility-spending spree. Bessent told the currency markets last week that he was “the house” and warned that nobody should bet against him. But the bond markets did and he lost. What weight will traders attach to his next pronouncement?
For a figure who it was initially hoped would be the rare adult in Donald Trump’s second administration, Bessent’s behaviour has turned noticeably adolescent. He recently described Canada as a “little yippy dog” biting at the heels of America’s German shepherd. At the Republican convention in Dallas last week, he warned that a Democratic midterm victory would result in a “socialist hellscape”. Then to the markets he said: “Look, if some of the Bloomberg Terminal bros are unhappy with what I’m doing, well, that’s too bad.”
Such comments might not raise eyebrows if another official, or indeed Trump, made them. But a Treasury secretary’s words are weighed differently. The same day that Bessent spoke in Dallas, bond markets rebuffed his $6bn intervention to bring down long-term interest rates. On Monday, the 10-year Treasury yield broke through the 5 per cent barrier, which left Bessent looking weak. But even the most plausible US Treasury secretary would find it hard to sway a trillion-dollar daily bond market turnover with a $6bn intervention.
It is also puzzling that Bessent thought his gambit was needed. A 5 per cent yield on the 10-year bond is unremarkable by the standards of the past 50 years. Moreover, persistently high US inflation and the huge debt-fuelled AI investment drive mean that he is swimming against the tide. It remains to be seen what the bond market will do if the US Federal Reserve lifts the short-term rate this week, as seems likely. The only safe bet is that it will enrage Trump, who is pressuring Kevin Warsh, the new Fed chair, as well as Bessent, to lower borrowing costs.
Yet the puzzle remains. What is the use of Bessent acting on Trump’s wishes if he is so quickly exposed as having failed? His abiding problem is that he can do little about the real drivers of higher US interest rates. A logical step would be to pledge to cut America’s budget deficit — debt interest payments now exceed the US defence budget.
But politics seems to be messing with Bessent’s head. In Dallas, he echoed other speakers in warning of Democrats bringing in Soviet-style economics. The nearest the convention came to Bolshevism, however, was when Trump promised to give every American adult a $5,000 “dividend” if the Republicans won in the midterms. This government giveaway would cost north of $1tn and lose much of its upside through higher interest rates. But Bessent leapt to his feet alongside colleagues.
That Trump’s gimmick would be unlikely to pass Congress — some Maga loyalists even had trouble with it — is not that reassuring. The markets have been put on ample notice that US public debt growth will continue to outstrip economic growth. Nothing that Bessent can say will realistically alter that. But he could at least try to conserve the weight of his words. Credibility is the most precious resource a Treasury secretary has.
The case for Bessent’s erratic actions is as follows. He is seeking to please one man. By showing Trump that he is a true believer, Bessent buys himself room to talk the president off the ledge. If that means Bessent has to act like the Pete Hegseth of the Treasury — bursting with market-defying testosterone — then so be it. But for such antics, perhaps Kevin Hassett, rather than Warsh, would be US Fed chair. Then the markets could legitimately panic.
Moreover, not every Bessent intervention has bombed. Against the odds — and in breach of precedent — he helped give Argentina’s Javier Milei an election victory last year by injecting $20bn in US “emergency” support. He also partly reversed the Japanese yen’s slide with his recent intervention. But these are slim pickings against his rapidly incinerating market reputation.
It is hard to see how he can get out of it. Trump never forgave his first Treasury secretary, Steven Mnuchin, for having recommended Jay Powell as Fed chair. Trump implied Powell had betrayed him by raising interest rates. Warsh will disappoint too. Yet Bessent is badly harming himself in his quest not to disappoint the president. As one Washington veteran quipped: “Bessent makes Steve Mnuchin look like Alexander Hamilton.”