History Says This Will Happen to Palantir Stock by 2028 | The Motley Fool
Palantir (PLTR +5.17%) has been an incredible stock to own over the past few years. It has become one of the most prominent AI companies in the country, and a host of companies and government agencies make use of its services. It has grown its sales at an incredible pace over the past few years, and its stock has soared as a result.
However, there’s one overarching question: Has Palantir’s stock gotten ahead of itself? I think history offers a pretty strong indication about the answer, and it’s not one that Palantir shareholders will be happy to hear.
Image source: The Motley Fool.
Competition is rising
Palantir made a name for itself by offering its customers a fairly easy plug-and-play AI software. Essentially, clients can easily deploy Palantir’s AI-powered analytics tool to mine their internal data for useful insights. The early iterations of its software were intended for government use, but eventually, the company found its way into the commercial marketplace. The combination of government and commercial AI has been a powerful one for Palantir, but it isn’t the only game in town anymore.

Today’s Change
(5.17%) $10.27
Current Price
$209.05
Key Data Points
Market Cap
Day’s Range
$198.30 – $209.58
52wk Range
$106.37 – $209.58
Volume
37.6M
Avg Vol
33.5M
Gross Margin
84.80%
Rising stars like Anthropic and OpenAI also have great AI products that companies can use, and these products could become more popular than Palantir’s, which could result in its growth slowing.
Wall Street analysts are already projecting just that. The consensus view is that Palantir will report that it grew by 84% in Q3, and that it will further slow to 75% in Q4, compared to 93% in Q2. Next year, the projected growth rate declines to 50%.
If that happens, the stock could be in trouble, as there is a ton of hoped-for growth already baked into the stock. However, Wall Street has been consistently wrong on its Palantir projections, as its growth rate has continued to accelerate quarter after quarter, even though the company’s own projections also indicated it would slow.
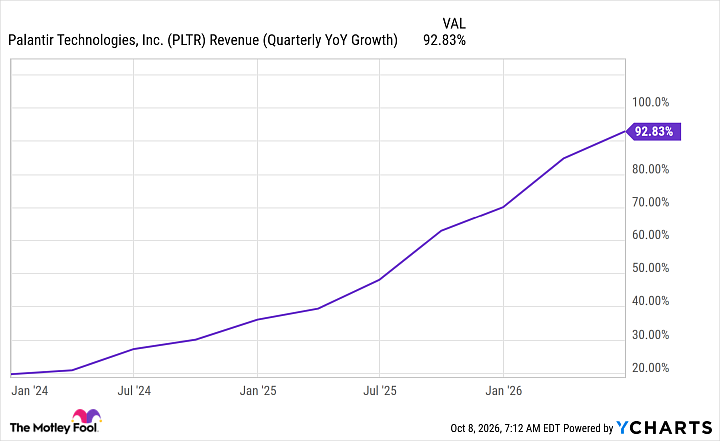
PLTR Revenue (Quarterly YoY Growth) data by YCharts.
Yet as more companies become comfortable deploying AI tools from giants like OpenAI and Anthropic, this may pose a sizable headwind for Palantir, since most of its platforms’ capabilities can be recreated for far less than it charges for a subscription.
That wouldn’t be great for the stock, and history has nearly countless examples of innovators that started as disruptors before being disrupted themselves. The main problem for Palantir’s stock is that it’s priced like the company has no competition.
Palantir’s stock is pricey
From a price-to-sales ratio standpoint, Palantir is very expensive at 81.
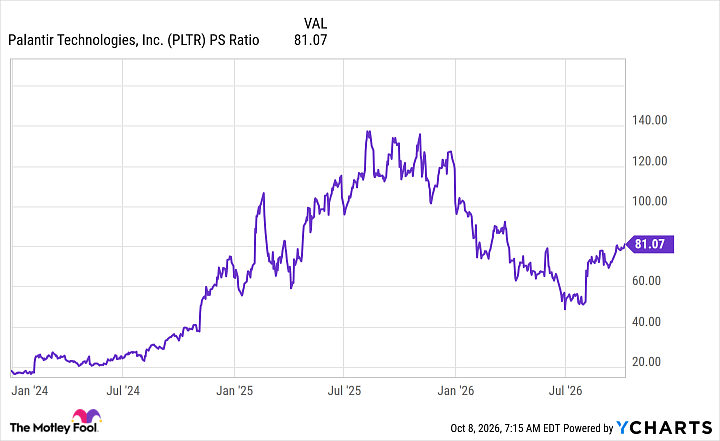
PLTR PS Ratio data by YCharts
Generally speaking, software stocks are considered expensive when they trade above 20 or 30 times sales, let alone triple or quadruple that level. For comparison, AI lab Anthropic is expected to go public with a market cap of about $2 trillion sometime in November. Back in July, Anthropic told investors that its annual run rate would be about $65 billion. If the market were willing to put a P/S valuation of 81 on Anthropic, that would give it an IPO market cap of $5.3 trillion.
As a group, companies that reach such high price-to-sales multiples have a terrible track record of long-term share price performance in the years that follow, as there is a lot of anticipated growth already priced into the stock. Even if Palantir can continue growing rapidly, its stock will spend a lot of time absorbing that growth while trading sideways to bring its valuation down to a more reasonable level. Or, it could be disrupted by one of the growing AI labs such as Anthropic or OpenAI, in which case the market could respond by selling it off. As a result, I think investors can expect lackluster returns from Palantir through 2028.