Sweetgreen Is Up 32% Since the Cyclospora Outbreak Ended. Is There More Room To Run? | The Motley Fool
Sweetgreen (SG +1.49%) has been a bitter pill to swallow for investors over the last two years, as the stock is down 80% from its peak in late 2024.
Sales growth at the fast-casual chain turned negative amid concerns about a lack of value in its menu, as its customer base has faced years of elevated inflation and the high cost of living. Additionally, Sweetgreen has faced headwinds related to a change in its loyalty program, and one-off events like the LA wildfires and the cyclospora outbreak. The company also sold the business that owns the Infinite Kitchen, though it retains the rights to use the food prep and expediting technology.
Of those challenges, the cyclospora outbreak was the most recent. Though Sweetgreen’s food was not implicated, as it doesn’t use iceberg lettuce, its association with salad led to a downturn in traffic.
In fact, Sweetgreen’s comparable sales were positive in the first days of July until the outbreak hit, and the company consequently cut its full-year same-store sales guidance to a 7%-8% decline, citing the impact of the outbreak, saying, “The pace and timing of recovery remain uncertain.”
Image source: The Motley Fool.
Sweetgreen rides a post-Cyclospora wave
On Sept. 11, the CDC declared that the cyclospora outbreak had ended. Sweetgreen jumped 5% on that day, and, after a brief setback, has rallied steadily since then, as the chart below shows.
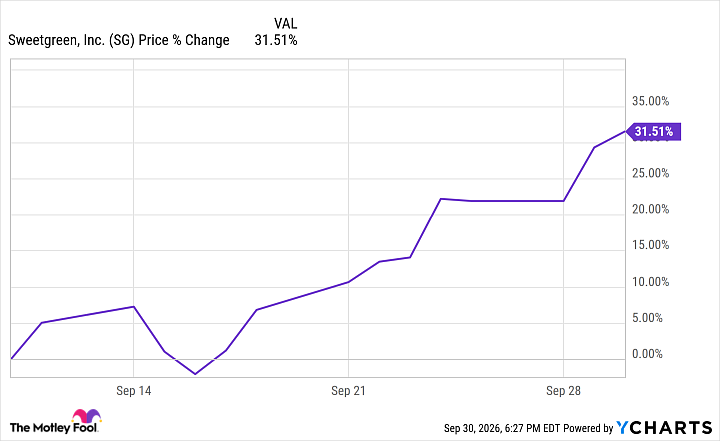
Sweetgreen stock is now up in eight of the last ten sessions, which includes a brief dip when it fell just 0.2%.
Is the Sweetgreen comeback finally here?
After six straight quarters of negative same-store sales growth, Sweetgreen’s return to positive growth in early July is certainly a bullish signal for the stock, and shares likely would have rallied following the second-quarter report had it not been for the cyclospora outbreak.
The brand’s new wraps appear to be resonating with customers, offering them a lower price point for a Sweetgreen meal, and other headwinds, like the change in its loyalty program, have rolled off.
Sweetgreen is making other moves that could also fuel its growth. It just hired Molly Baz, who has written two best-selling cookbooks, as its first Chef in Residence. Baz is creating a new limited-time menu that is running for six weeks staring on Sept. 29. The move should help Sweetgreen continue to build buzz and gain momentum as it moves past the impact of the cyclospora outbreak.
Sweetgreen also continues to open new stores, a reminder that it still has a lot of growth potential. The company finished the second quarter with 285 locations across the country, and sees room in the market to reach at least 1,000 stores. At one point, the company aimed to reach that goal by 2030, though that now seems out of reach. Still, the long-term growth potential is attractive.

Today’s Change
(1.49%) $0.13
Current Price
$8.87
Key Data Points
Market Cap
Day’s Range
$8.64 – $9.00
52wk Range
$4.49 – $10.63
Volume
5.6M
Avg Vol
5.7M
Gross Margin
92.05%
Sweetgreen could still soar
The biggest challenge for Sweetgreen is returning to same-store sales growth. If the company can achieve that, it can start to solve its other problems, including reaching generally accepted accounting principles (GAAP) profitability, and eventually accelerating its store openings. Sweetgreen has a market cap of just $1 billion, meaning the stock could easily double or better from here if it can return to growth. It’s been priced like a failing business, but that may prove temporary.
We won’t get an earnings update from the company for another month, but with the cyclospora outbreak behind it, we’re likely to see an improvement in full-year guidance. If the company can get back to positive comparable sales, the stock could move a lot higher from here.