Is Now a Good Time to Buy Lockheed Martin? | The Motley Fool
There was plenty to like about Lockheed Martin‘s (LMT +2.42%) earnings report on Oct. 22. The aerospace and defense manufacturer raised its full-year guidance for the second quarter in a row while beating Wall Street’s third-quarter estimates. While the stock has risen more than 20% year to date as of this writing, Lockheed remains a solid buy for long-term investors.
LMT Lockheed Martin
$604.18+$14.27 (+2.42%)
NYSE · As of 4:00 PM ET 10/23/26
First and foremost, Lockheed’s third-quarter sales grew 11% to $20.7 billion. Earnings per share beat analysts’ expectations by nearly $0.50 at $7.97. All four of Lockheed’s segments grew, with the Missiles and Fire Control business having the greatest gain, increasing 14% from this quarter last year.
Lockheed’s management now expects sales to top $80 billion and free cash flow of $7.8 billion to $8 billion in 2026. The free cash flow number increased by $800 million from last quarter. Lockheed also increased its dividend again, marking 24 consecutive years of increases.
Image source: Getty Images.
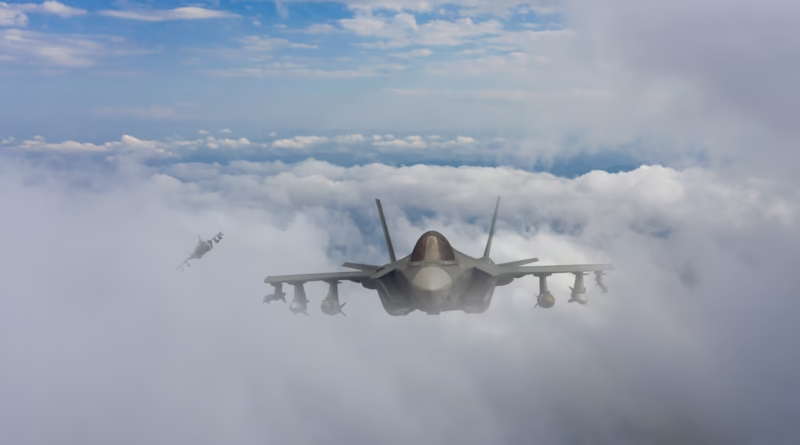
The stock is really a buy because of the growth in backlog, which provides substantial revenue visibility. The backlog grew 27% to $292 billion this quarter. In particular, Lockheed signed multiyear deals for a PAC-3 interceptor and 850 F-35 jets.
Of course, Lockheed’s success depends on its ability to execute efficiently and effectively, but for buy-and-hold investors, the backlog, rising guidance, and consistently growing dividend are excellent reasons to purchase the stock. Shares are still trading at a reasonable price. The company’s forward and trailing price-to-earnings ratios are in the teens, and the dividend yield is respectable, currently around 2.5%.
Catie Hogan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Lockheed Martin. The Motley Fool has a disclosure policy.